
Mortgage Tree Report
Independent arboricultural reporting when a mortgage lender, valuer or surveyor asks for specialist information about trees near a property.
Explore service →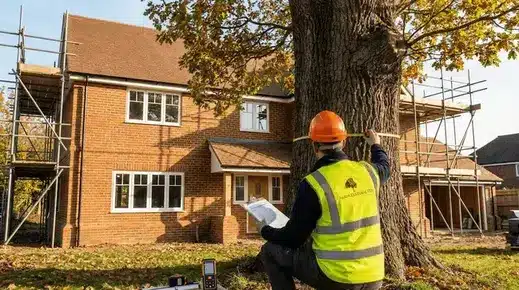
Mortgage tree report enquiries usually arrive at the worst possible point in a property transaction: after the valuation, during conveyancing or just before exchange. We make the next step simple. Upload the lender, valuer or surveyor wording, add the property address and tell us your deadline. A consultant can review what has actually been requested before the work is priced.
Independent arboricultural reporting across London and the South East · UK-wide mortgage tree report guidance.
Upload the lender wording, survey extract or insurer wording and send the property details through the built-in form. Every enquiry is stored on MortgageTreeReport.uk and emailed through for consultant review.
The site is designed for the real-world wording buyers see from banks, valuers and surveyors. The strip below is presented as a familiar lender landscape rather than a claim of formal endorsement.
A generic tree survey is not always what the mortgage lender asked for. The useful starting point is the written condition or survey recommendation. That lets the inspection and report focus on the property, the relevant trees and the professional question holding up the transaction.
Independent arboricultural reporting when a mortgage lender, valuer or surveyor asks for specialist information about trees near a property.
Explore service →A focused tree report prepared around the exact wording supplied by a mortgage lender or lending underwriter.
Explore service →Professional arboricultural evidence for a mortgage application, purchase, remortgage or lender condition.
Explore service →A pre-purchase arboricultural report for buyers who want clearer information about significant trees affecting a property.
Explore service →Specialist tree advice following a Level 2 or Level 3 survey, valuation or recommendation for further arboricultural assessment.
Explore service →Independent tree condition and property-related information where an insurer requests arboricultural evidence.
Explore service →We keep the process focused on the property transaction. The website captures the details directly, so you do not need to leave MortgageTreeReport.uk to start the enquiry.
Upload or paste the lender, valuer or building-surveyor wording and add the property address.
A consultant reviews what is actually being asked and identifies the appropriate arboricultural inspection.
The relevant trees, their condition and their relationship with the property are inspected where required.
The completed report is supplied digitally for the buyer, broker, surveyor or lender to review.
The service area covers London and the wider South East. Regional and town pages help buyers find locally relevant information while the guides remain useful to people dealing with lender requests anywhere in the UK.
Our guides are written around the questions buyers actually face: lender conditions, Level 2 and Level 3 surveys, trees near foundations, report timescales, subsidence concerns and what documents to send.
Why lenders sometimes ask for specialist arboricultural evidence and what to do next.
Read the guide →A practical guide to inspection scope, tree condition, property relationships and recommendations.
Read the guide →What qualifications and professional independence matter when a lender asks for a specialist report.
Read the guide →What affects professional fees and why the lender wording should be reviewed before pricing.
Read the guide →How site access, urgency and report scope influence turnaround during a property transaction.
Read the guide →How to make sure the report addresses the lender or valuer request rather than a generic tree question.
Read the guide →MortgageTreeReport.uk is built to generate leads directly on-site, but buyers who want wider arboricultural background can also explore the broader consultancy resources at Arbor Cultural. This gives the site a genuine knowledge connection without sending the quote process away from the website.
The form, lead capture and email workflow stay on MortgageTreeReport.uk so buyers can request help without leaving the website.
Request a quote →For wider consultancy background, planning context and arboricultural information, see Arbor Cultural.
Visit Arbor Cultural →Service, guide and location pages are interlinked so local searchers can move from regional to town-level pages without hitting duplicate copy.
Explore areas →The request normally starts because somebody in the property chain has spotted a tree-related uncertainty. Our job is to turn that uncertainty into a clear arboricultural question and answer it proportionately.
Large trees close to houses can attract cautious wording in a valuation even when nobody has suggested that the tree is unsafe. The lender may simply want an independent opinion on condition, proximity, foreseeable management or whether anything obvious warrants further investigation. That is very different from commissioning tree surgery.
For buyers, this matters because the report should not create unnecessary alarm. The inspection should describe what can actually be observed, explain sensible limitations and make recommendations that are proportionate to the evidence. A mature tree is not automatically a mortgage problem, and removal is not the default answer.
If a Level 2 or Level 3 survey says “obtain specialist arboricultural advice,” send the whole paragraph. The words before and after that sentence often show whether the concern is condition, proximity, ownership, future maintenance or possible structural influence. That context helps the consultant prepare the right report instead of guessing.
The same applies to lender emails. If the bank uses a phrase such as “report acceptable to the lender,” keep the wording intact. The consultant can then make sure the written report is structured around the point that needs to be reviewed.
A routine lender report is not the same thing as a subsidence investigation. If the house already has cracking, distortion, movement or an active insurance claim, say so before the site visit is booked. The arboricultural evidence may still be useful, but the wider question can involve structural engineering, soils, drainage or monitoring that sits outside a normal purchase report.
Being open about damage at the start is not a disadvantage. It prevents the wrong service being commissioned and gives the property team a clearer idea of what evidence is still missing.
At the end, the buyer should understand which trees were relevant, what was observed, whether any obvious management is recommended and what limitations remain. The lender should have a professional document that addresses the condition it raised. The broker and conveyancer should know what, if anything, needs to happen next.
That is why we collect the lender wording, property details and deadline through the website before the report is priced. Good scoping is part of good reporting.
Start with the wording you have been given. You do not need to know the technical report name before sending the enquiry.
A lender or valuer may want specialist arboricultural evidence where trees are close to the property, appear significant or have been flagged by a survey. The exact wording should guide the report scope.
Send the property address and the exact lender, valuation or survey wording. Add your deadline and attach the relevant survey page if you have it.
Not always. A routine mortgage tree report is different from a damage-led subsidence investigation. If the property already has cracks, movement or an active claim, say so at the start.
Yes. Choose “Not sure — please advise” and paste the wording you were given. The point of the form is to let the consultant review the request before you commission the wrong service.
The direct inspection service is focused on London and the South East. The guide and advice library is written for mortgage tree report questions across the UK.
Upload it with the property address. The enquiry stays on MortgageTreeReport.uk and is sent directly for consultant review.